Logs and lumber

Forest Products Week 2026

By Brian Cole, Wisconsin DNR Forest Product Specialist

Wisconsin’s forests cover nearly half of our state and are a vital part of our collective history, culture and economy. Likewise, the F+orest Products industry provides valuable jobs and contributes significantly to the economy. Forest Products Week offers an opportunity to learn about sustainable forest practices and to develop an appreciation for the valuable resources that Wisconsin forests provide.

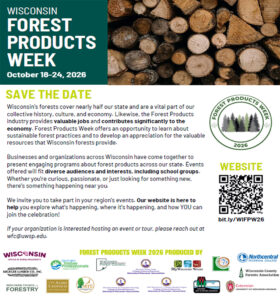
Forest Product Week 2026 starts on Sunday, Oct. 18. Tours and special events will be hosted throughout the week at various locations, including logging sites, sawmills, paper manufacturers, secondary and urban wood manufacturers. Please save the date and join us at one of our events.

National Forest Products Week was established in 1960 with a proclamation brought forth from Congress and approved by President Kennedy, Public Law 86-753 (36 U.S.C. 123). The language in the proclamation cited the importance of forest products, dating back to the country’s founding and its ever-demanding growth cycles. A key sample from that first resolution states:

WHEREAS in order to reemphasize to each citizen in the United States the importance and heritage of our vast forest resources which are inseparably tied to our present and our future: Now, therefore, be it

Resolved by the Senate and House of Representatives of the United States of America in Congress assembled, That:

The seven-day period beginning on the third Sunday of October in each year is hereby designated as National Forest Products Week, and the President is requested to issue annually a proclamation calling upon the people of the United States to observe such week with appropriate ceremonies and activities.

From building materials and paper products to furniture and bioenergy, wood has a central tie to our daily lives. Today, decades after its launch, National Forest Products Week celebrates one of our nation’s most valuable resources and the people who transform trees into countless products that improve our lives.

For more information and to learn about events being held across the state, please visit the Wisconsin Forestry Center’s website.

Forest Products Highlighted At The Wisconsin State Fair

By Brian C. Cole, Wisconsin DNR Forest Product Specialist

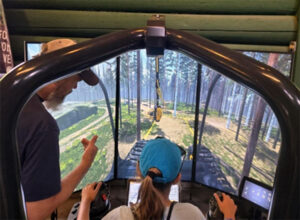
person at the control of a piece of heavy equipment.

Photo Credit: Wisconsin Forestry Center

At this year’s Wisconsin State Fair, the Wisconsin Department of Natural Resources’ Forest Products Services program, in conjunction with the University of Wisconsin – Stevens Point Wisconsin Forestry Center, showcased the economic importance of Wisconsin’s forest products industry.

This included pulp and paper, lumber and non-timber forest products like maple syrup, as well as advanced forest products like biochar and sustainable aviation fuel. Wisconsin’s $27 billion forest products sector is leading the way in forest products development and sustainable forest management.

Along with forest products, fairgoers learned about forest health issues, invasive species, Wisconsin’s forest trees and tree identification. The big attraction was the Ponsse North America harvester simulator. Fairgoers had a chance to virtually operate a Ponsse Scorpion dangle head harvester and take part in a virtual, sustainable, cut-to-length harvest. Fairgoers learned about modern-day logging and why a sustainable harvest is needed for forest management.

Latest Timber Products Output Survey Results For Wisconsin Available

By Ryan Heiderman, Wisconsin DNR Forest Inventory Analyst

Recently, the United States Forest Service released updated data summaries from the Timber Products Output (TPO) survey, a component of the National Resource Use Monitoring (NRUM) program. This program falls under the larger Forest Inventory and Analysis (FIA) umbrella of programs. New data download, factsheets and other data products can be found on the NRUM webpage.

TPO is a survey on manufacturers who use harvested wood products that reports size of facilities, products manufactured, manufacturing capacity and other important indicators of the forest products industry. TPO data is reported for individual states based on an annual survey. The survey is administered by the Wisconsin DNR’s Forest Products Services team in partnership with the USFS. Annually, the team surveys approximately 85 primary wood processing facilities across Wisconsin. In addition to providing valuable industry data about roundwood production and wood residue generation, the survey offers an opportunity to connect with mills throughout the state, strengthening relationships and providing insight into current market conditions and trends within Wisconsin’s forest products industry.

chart

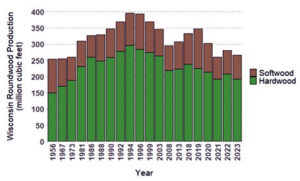
Figure 1: Annual hardwood and softwood roundwood production trends of Wisconsin’s primary wood-using mills. Data is sourced from various USFS publications reporting on the Wisconsin’s timber industry and wood product output. / Graphic Credit: Wisconsin DNR

The most recent TPO data is available for Wisconsin survey years 2022 and 2023. The most recent data shows 265 million cubic feet of roundwood production in Wisconsin mills, with about 75% of this production coming from hardwood species. Historic TPO data can be found in numerous reports published by the USFS dating back almost 100 years (Figure 1). Roundwood production ramped up in the 1980s as many of the cutover lands were becoming mature again and peaked in the 1990s. Wisconsin experienced a decline in large sawmills and paper mills from 1999 through 2008, with production subsequently declining during the 2008 financial crisis. Production rebounded slightly and again decreased during the COVID-19 years.

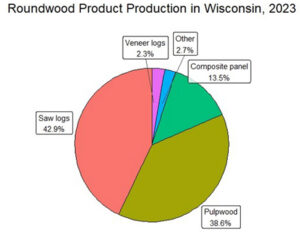
Roundwood is processed into different products depending on the species, tree size, market conditions, harvest site proximity to mills and a variety of other variables. In 2023, the majority of roundwood was processed into two major product categories accounting for over 80% of production: sawlogs and pulpwood (Figure 2).

chart

Figure 2: Roundwood product production by product class. / Graphic Credit: USDA Timber Products Output, Wisconsin, 2023

Sawlogs accounted for 43% of production and includes roundwood logs and bolts processed at sawmills into a variety of sawn products such as lumber, cants, squares and blanks. Red pine is the most commonly utilized species for sawlogs, accounting for approximately one-third of production. Red oak (18%) and sugar maple (11%) follow behind red pine in sawlog production.

Pulpwood accounted for 39% of production and includes roundwood logs, bolts and chips used in the manufacture of wood pulp for making paper and paperboard products. Many species are utilized for pulpwood including both soft (23%) and hard maple (15%), red (16%), white (6%) and jack (2%) pine, aspen (14%), and red (9%) and white (2%) oaks.

The third most common product made from roundwood are composite panels (13.5% of roundwood production), which include many different reconstituted wood products such as chip board, flake board, oriented strand board and various engineered lumber. The majority of composite panel roundwood is aspen (82%) with some basswood (14%) and other common hardwood species.

Extending The Health Benefits Of Urban Trees

By Dwayne Sperber, President, Wudeward Urban Forest Products, and Founding Member, Urban Wood Network
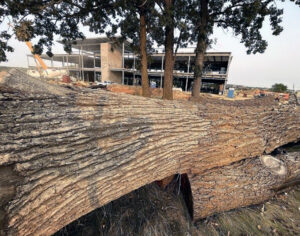
fallen logs

Photo Credit: Dwayne Sperber

Wisconsin’s 2020 Statewide Forest Action Plan recognizes urban and community forests as essential tools for achieving economic, environmental, social and public health goals. To advance those goals, the plan encourages multi-sector partnerships, engagement with new audiences and the use of urban wood. A recent project at the Medical College of Wisconsin illustrates how these priorities can be realized when those who manage urban and community forests are connected with established higher-use utilization pathways and the professionals committed to recognized industry standards who support them.

During site preparation for new student housing at the Medical College of Wisconsin, trees designated for removal were evaluated to determine their highest and best use. Logs suitable for higher-use applications were preserved and directed into a standardized urban wood utilization pathway where they can ultimately become durable wood products.

How Can The Benefits Of Urban Trees Continue After Removal Becomes Necessary?

The health benefits of urban and community trees are well documented and continue to be advanced through DNR initiatives, the Wisconsin Urban Forestry Council’s Public Health & Trees Issue Group, the Arbor Day Foundation’s Tree Campus Healthcare program and a growing body of research examining the relationship between nature, the built environment and human well-being.

While preserving healthy trees remains the priority, removal is an inevitable part of managing urban and community forests. Sustainable urban forestry recognizes that the environmental, economic and public health benefits of trees need not end when their standing life has. The answer depends not only on how urban and community forests are managed, but on partnerships with organizations and professionals committed to recognized industry standards and higher-use utilization.

Across Wisconsin, municipalities, developers, healthcare organizations, educational institutions and professionals who influence the built environment are increasingly recognizing removed trees as renewable natural resources. Working with Urban Wood Network members and other industry partners committed to recognized standards helps connect those who manage urban and community forests with established utilization pathways and manufacturers seeking sustainable, renewable materials. Without awareness of these pathways and the professionals who make them possible, many trees suitable for higher-use applications would continue to be managed as low-value material or waste.

Recognizing that long-term success depends on industry standards, utilization pathways and market awareness, the Urban Wood Network (UWN) was established to connect those who manage urban and community forests with the professionals and organizations committed to the responsible use of urban wood. Supported by the U.S. Forest Service and acknowledged by the DNR, Wisconsin Council on Forestry and other partners, UWN helps strengthen the relationships that move removed trees into consistent, higher-use applications.

This collaborative approach reflects nationally recognized sustainable urban forestry practices that encourage organizations to work with urban wood professionals, support recognized industry standards and build long-term utilization partnerships.
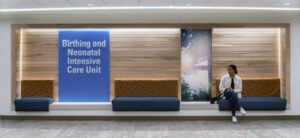
 

woman sitting in front of sign

Photo Credit: Dwayne Sperber

Research supporting biophilic design continues to demonstrate that stronger connections to nature within the built environment can reduce stress, improve well-being and support healing. These evidence-based design principles are increasingly influencing healthier and more sustainable buildings and are reflected in initiatives led by the American Institute of Architects.

The Medical College of Wisconsin project demonstrates how collaboration between a developer, those who manage urban and community forests, industry partners and public agencies can transform necessary tree removals into opportunities that benefit people well beyond the project site. Trees removed during one project can continue serving communities for decades through the buildings, products and spaces where they are ultimately used.

As communities pursue public health, sustainability, resilience and carbon reduction goals, urban forestry is increasingly positioned to contribute to each of these priorities. By connecting those who manage urban and community forests with recognized standards, qualified professionals and established utilization pathways, Wisconsin can continue advancing the vision outlined in its Statewide Forest Action Plan, ensuring that the benefits of urban trees continue long after their standing life has ended.
New Publication Examines Wisconsin Consumer Perceptions Of Wood Species

By Scott Lyon, Wisconsin DNR Forest Products Team Leader

A new study published in the Forest Products Journal examines how Wisconsin consumers perceive established and underutilized wood species and identifies opportunities to expand markets for Wisconsin-grown wood products.

“How Established and Underutilized Wood Species Are Perceived: Perspectives from Wisconsin Consumers” evaluated consumer perceptions of 10 Wisconsin-native wood species, including walnut, cherry, oak, maple, ash, white pine, tamarack, honey locust, and ambrosia maple. The study collected 326 responses from consumers attending home shows in Madison and Appleton in 2023.

The results demonstrate that several underutilized species compare favorably with more established species. Honey locust and ambrosia maple, for example, were selected among consumers’ top three preferred species by 33.2% and 30.2% of respondents, respectively. Tamarack was selected by 17.5%, while ash was selected by 18.3%. Overall, the findings indicate that consumers have diverse preferences and that underutilized species have potential for greater use in value-added products.

The Wisconsin DNR Forest Products Services team played an important role in the research. DNR Forest Products Team Leader Scott Lyon and Forest Products Specialist Alex Anderson are co-authors of the publication. The study also incorporated a rustic-to-clean perception scale at the request of the Wisconsin DNR to better understand opportunities for utilizing low-quality fiber.

The research provides useful information for Wisconsin forest products manufacturers, designers, marketers, and others working to develop markets for underutilized wood resources. Understanding how consumers perceive characteristics such as warmth, durability, sustainability, formality, and rustic appearance can help businesses select species and develop products and marketing strategies that better align with consumer preferences.

The study highlights the potential to expand the use of Wisconsin’s diverse wood resources by matching species characteristics with consumer preferences and product design objectives. This type of market research supports the DNR Forest Products Services team’s efforts to promote value-added utilization and develop new markets for Wisconsin forest resources.

The entire publication is available online.

New Report Series Tracks Post-Pandemic Footprint Of Northeast-Midwest Forest Products Industry

By Ram Dahal, Wisconsin DNR Forest Economist

The Department of Forestry at Michigan State University, on behalf of the Northeast-Midwest State Foresters Alliance Forest Markets & Utilization Committee, has released a new, USDA-supported report series detailing the economic contributions of the forest products sector. This project consists of one comprehensive regional report and 20 state-specific reports.

The study utilized 2023 IMPLAN (Impact Analysis for Planning) data, the latest data available at the time of the analysis and compared it to the previous benchmark study completed in 2020 which relied on 2017 data. Looking at these timelines side by side, the reports show how the forest products sector reacted to COVID-19 supply chain issues and give us an updated look at its current post-pandemic health.

By assessing core economic indicators including employment, output, labor income and value-added, this series provides metrics that state agencies and industry leaders can use to monitor forest resource economic health, justify strategic capacity-building investments, target local workforce development, and shape regional forest management policies to actively strengthen the sector.

In the Northeast-Midwest region, the forest products industry acts as a $203 billion industry, directly supporting over 514,000 jobs. When accounting for the ripple effects throughout supply chains and household spending, the sector’s total footprint grows to a massive $387 billion and over 1.28 million jobs. This shows a substantial increase from the 2017 report, which recorded a $327 billion total footprint, highlighting the sector’s long-term growth and its powerful ability to support wider employment.

Compared to 2017, the Northeast-Midwest region’s forest products sector saw a 5.1% decline in direct employment and a 2.9% drop in gross output. Despite this, the industry showed resilience with a 1.7% net gain in value-added wealth, reaching $63 billion, while individual worker productivity increased to $395.27 thousand in output per job.

The report also reveals distinct manufacturing and labor patterns across individual states. Pennsylvania leads the region in direct employment, followed by Wisconsin, Ohio, Indiana, and Michigan. However, when measuring value of production, Wisconsin takes the top spot, followed by Pennsylvania, Ohio, Michigan and Indiana. Ultimately, these rankings demonstrate that while some states serve as major labor hubs, others excel in high-value, high-output production, providing each state agency with targeted insights to strengthen their specific local advantages.

These state and regional reports provide a clear, reliable guide for anyone looking to support the regional forest economy. This analysis helps state agencies, industry groups, and investors track sector health and create better workforce and marketing strategies. The complete series of state and regional reports is now available through the Michigan State University FERM Lab Forest Product Industry portal.

Wisconsin Forest Products Industry Navigates Challenging Market Conditions

By Elle Soderberg, Wisconsin DNR Forest Products Specialist

Wisconsin’s forest products industry continues to navigate a challenging market environment as mills, loggers and other industry partners respond to changing demand, limited pulpwood markets and broader economic uncertainty.

The Wisconsin DNR Forest Products Services team regularly connects with forest industry partners throughout the state to better understand regional and statewide market conditions. Recent conversations indicate that while portions of the industry remain stable, pressure continues across several key markets.

One of the most significant challenges remains Wisconsin’s pulp and paper sector. Recent mill closures have reduced available outlets for pulpwood and disrupted traditional fiber flows. The Ahlstrom mill in Kaukauna has resumed purchasing wood, but volumes remain limited as the market continues to adjust following the closure of Ahlstrom’s pulp mill in Mosinee. Suppliers with established contracts have generally experienced typical seasonal fluctuations, while those displaced by mill closures have faced greater difficulty finding new markets.

Conditions in the hardwood lumber market also remain difficult. Timber is generally available, but mills report that log costs remain high relative to finished lumber prices. Weak housing and construction activity has further reduced demand for hardwood products traditionally used in flooring, cabinetry and trim. White oak has been particularly affected, with green 4/4 FAS white oak prices falling nearly 24% over the past year and approximately 30% compared with two years ago.

Logging operations continue to feel the effects of these market conditions. Limited pulpwood outlets, changing weather patterns, increased fuel prices, and workforce availability remain persistent concerns. Wisconsin has ample harvestable timber, but some landowners are finding it increasingly difficult to secure logging contractors, while reduced demand is limiting economically viable markets for harvested material.

There are, however, some positive market signals. Industry contacts reported stronger demand for hickory, cherry and hard maple, while some Wisconsin and Lake States producers have experienced improved export opportunities. Strong demand from European and Asian markets has helped certain producers offset weakness elsewhere in the market.

Other wood markets remain mixed. Hardwood pallet production continues to lose market share to softwood, creating concern about the stability of low-grade markets. Railroad tie demand is also expected to soften, with the Railroad Tie Association forecasting demand of approximately 19.7 million ties in 2026 and 19.2 million in 2027.

Looking ahead, Wisconsin’s forest products industry is expected to remain cautious. While some sectors are showing signs of stability or growth, overall activity remains below full capacity. Future conditions will depend heavily on pulpwood market adjustments, housing and construction activity, broader economic conditions and the industry’s ability to adapt to changing markets.

Timber Bridges For Stream Crossings Now Available

One of the temporary bridge structures for stream crossings that will be available from selected Wisconsin Department of Natural Resources and private facilities for use by loggers who are working on timber sales. / Photo Credit: Wisconsin DNR

Through a U.S. Forest Service grant, along with a partnership with the Great Lakes Timber Professionals Association, the Wisconsin Department of Natural Resources (DNR) is soon going to be able to provide temporary bridge structures for stream crossings. Continue reading “Timber Bridges For Stream Crossings Now Available” →

A Closer Look At Red Pine In Wisconsin

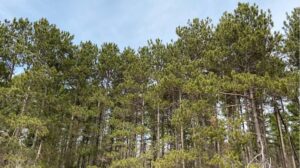
Wide-angle photo of a red pine tree stand in Wisconsin.

A stand of red pine trees towers over its Wisconsin stand. / Photo Credit: Wisconsin DNR

By Ryan Heiderman, DNR Forest Inventory Analyst
Ryan.Heiderman@wisconsin.gov

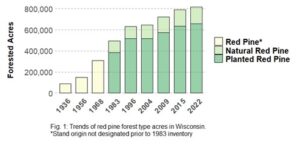
Of Wisconsin’s almost 17 million acres of forest land, the red pine forest type currently covers approximately 815,000 acres. Of those red pine acres, 80%, or 656,000 acres, are planted.

Overall, the acres of red pine have increased substantially since the cutover period of the early 1900s (Figure 1), particularly from planted red pine. In the 1939 report summarizing Wisconsin’s first periodic forest inventory, the authors give a dire warning stating that, with the exception of jack pine, the pine forests are almost gone, having been depleted and deforested in the decades prior.

Chart showing trends of red pine forest type acres in Wisconsin

Chart showing trends of red pine forest type acres in Wisconsin. The asterisk indicates that stand origin was not designated prior to the 1983 inventory. / Graphic Credit: Ryan Heiderman, Wisconsin DNR

This early inventory indicated much of the deforested sandy pine forest had become occupied by aspen, paper birch and scrub oak. They went on to say while natural regeneration might be expected eventually, indications were that it would be slow, and planting seemed to be the only recourse if early reforestation was to be accomplished.

Reporting on the next periodic inventory in 1956, the authors highlighted that red pine acres were ‘coming back’ and white pine acres fading. They reported that much of the tree planting that had been done since the previous inventory was mostly red pine. Echoing the advice from the earlier inventory report, the authors again stated the importance of forest planting – saying reforestation could increase the acreage of productive forest land, but the planting job was a big one. At the time, they reported some 148,000 acres of the red pine forest type. They reported that over half (53%) of these red pine acres were on public lands. Today, more than 60% of red pine acres are in privately-owned forests.

Continue reading “A Closer Look At Red Pine In Wisconsin” →

Eastern White Pine CLT Research Moving Along

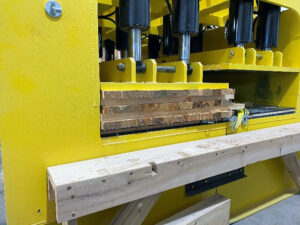
A five-ply panel of Eastern white pine from Wisconsin being formed into cross-laminated timber in a press at Michigan Technological University. / Photo Credit: Wisconsin DNR

By Alex Anderson, DNR Forest Products Specialist, Tomahawk
Alexander.Anderson@wisconsin.gov

As part of the Wisconsin Department of Natural Resources Forest Products Services mandate to explore new markets for species considered underutilized in the state, a research project was proposed to evaluate the viability of Eastern white pine (EWP) in cross-laminated timber (CLT) panels.

CLT has become increasingly popular in the U.S. during the last decade-plus, after the product was determined to be an effective alternative to traditional concrete and steel construction for multi-story construction in Europe. It is created by pressing dimension lumber (2x4s and 2x6s, typically) into large panels where each layer runs perpendicular to those above or below it, similar to plywood. This construction method allows for large structural panels to be created entirely from wood.

Continue reading “Eastern White Pine CLT Research Moving Along” →